Buying your first home in the Tri-Valley in 2026 comes down to three things: knowing which California first-time buyer programs you qualify for, getting honest about what you can afford in Livermore, Pleasanton, Dublin, San Ramon, or Danville, and working with someone who knows these neighborhoods street by street. This guide walks you through all three so your first offer is a confident one, not a guess.
In NAR’s 2025 Profile of Home Buyers and Sellers, first-time buyers were 21% of all buyers, a record low (transactions from July 2024 to June 2025). You’re in good company, and the path is more navigable than it looks from the outside.
Key Takeaways
– First-time buyers were 21% of all U.S. purchasers, a record low (National Association of REALTORS®, 2025).
– California programs like CalHFA loans and MyHome down payment assistance can lower your upfront cash, but terms and limits change yearly, so always verify current eligibility.
– The Tri-Valley is a high-cost market, so a realistic budget and a local agent matter more here than almost anywhere.
What Counts as a First-Time Home Buyer in California?
You may be a “first-time buyer” even if you’ve owned before. CalHFA defines a first-time homebuyer as someone who has not owned and occupied their home in the last three years and has not lived in a home owned by a spouse in that time, and notes that exceptions may apply (CalHFA). That reopens the door for plenty of people who assume they’ve missed their chance.
That three-year window matters. If you sold a home during a divorce, a relocation, or a tough financial stretch more than three years ago, and haven’t lived in a home your spouse owned since, you may qualify again. Programs change their fine print often, so confirm the current definition directly with CalHFA or your loan officer before you count on it.
Why does this matter for you? Because first-time status is what opens CalHFA’s MyHome down payment assistance, which requires it (CalHFA). It’s worth a five-minute eligibility check before you assume you’re shut out.
What First-Time Home Buyer Programs in California Exist in 2026?
CalHFA (the California Housing Finance Agency) pairs its conventional and FHA first mortgages with the MyHome Assistance Program, a deferred-payment junior loan for down payment and/or closing costs (CalHFA).
Here’s the part to take seriously: program names, funding levels, income caps, and assistance amounts change from year to year, and funds can run out mid-year. Do not rely on any specific dollar figure or rate you read online, including here. Treat the descriptions below as a general map, then verify the current 2026 terms with CalHFA and a CalHFA-approved lender before you plan around them.
A few program types to ask about:
- CalHFA first mortgages (conventional and FHA): the primary loan, offered through approved lenders.
- MyHome Assistance Program: a deferred junior loan for down payment and/or closing costs, repaid when you sell, refinance, or pay off the first mortgage.
- Dream For All Shared Appreciation Loan: CalHFA down payment and/or closing cost assistance for first-generation homebuyers. When you sell, transfer or pay off the first mortgage, you repay the original amount plus a share of the home’s appreciation. It opens in voucher rounds, so check whether a round is open (CalHFA).
- Local and county programs: Alameda County’s AC Boost program has offered its own down payment assistance loans, though its pre-application period closed May 15, 2024; ask your lender or the county about current status and any other local programs.
For a closer look at how these fit a Tri-Valley purchase, our buyer resources page is a good next stop. CalHFA does not take applications directly; you apply through a CalHFA-approved lender or Preferred Loan Officer (CalHFA).
Worth checking: CalHFA tells buyers to check with local housing authorities and agencies for other financing options (CalHFA), and it allows MyHome to be layered with other down payment assistance loans or grants as long as MyHome stays in second lien position (CalHFA). Ask your lender which city or county programs are open when you buy.
How Much Down Payment Assistance Can You Get in California?
Down payment assistance in California is typically structured as a deferred or “silent” second loan rather than a cash gift, which means you borrow the help and repay it later. How much you can get depends on the program. CalHFA’s MyHome Assistance Program, for example, is a deferred-payment junior loan of up to 3.5% of the purchase price or appraised value, whichever is less, with a CalHFA FHA first mortgage, or up to 3% with a CalHFA conventional loan (CalHFA).
Treat that cap as a starting point, not a promise, and be skeptical of any assistance figure that comes without a current source. Confirm today’s numbers with CalHFA and a lender, because a figure that was accurate last year may be different, or the program may be paused for funding.
What stays consistent is the structure: assistance usually sits behind your main mortgage as a deferred loan, repaid when you sell, refinance, or pay off the home. Knowing that upfront helps you plan your long-term equity, not just your move-in day. If you’re weighing how that affects your future sale, our free home valuation tool is a useful way to start thinking about equity from day one.
How Much House Can You Afford in the Tri-Valley?
A common starting point is the 28/36 rule: aim to keep housing costs at 28 to 35 percent of your gross monthly income and total debt payments under 36%, a guideline echoed by the Consumer Financial Protection Bureau (CFPB). It’s a sanity check, not a hard ceiling, but it keeps your first purchase from becoming a monthly squeeze.
The Tri-Valley raises the stakes because it’s a genuinely high-cost market. California’s homeownership rate ran from 55.3% to 56.8% in 2023, well below the national rate of 65.7% to 66.0% (U.S. Census Bureau, Housing Vacancies and Homeownership survey), which tells you affordability is the central challenge for California buyers, not a footnote.
So how do you make it work here? Run your real numbers before you fall in love with a listing:
- Get pre-approved first. A lender will verify income, debt, and credit, and hand you a price range grounded in reality.
- Budget beyond the mortgage. Property taxes, insurance, HOA dues (common in Dublin and San Ramon newer communities), and maintenance all count.
- Match the city to the budget. Entry prices vary across Livermore and Pleasanton, and a local agent can point you toward the pockets that fit.
- Keep a cushion. Leave reserves for the first year of surprises, not just the down payment.
Want a deeper read on one city’s pricing? Our guide to Livermore home values in 2026 breaks down what your money actually buys there.
What Are the Steps to Buy Your First Tri-Valley Home?
The home-buying process follows a predictable sequence, and knowing it removes most of the anxiety. Here’s the path from pre-approval to closing:
- Check your credit and savings. Pull your credit, knock down high-interest debt, and tally your available cash.
- Get pre-approved. A lender confirms your budget and signals to sellers that you’re serious.
- Explore programs. Ask your lender about CalHFA and any county assistance you may qualify for.
- Tour with a local agent. This is where Tri-Valley knowledge pays off, from school boundaries to commute routes.
- Make a strong offer. Your agent helps you price it right and structure terms that compete without overreaching.
- Inspections and appraisal. Verify the home’s condition and confirm value with your lender.
- Close and get your keys. Sign, fund, and record, and the home is yours.
A tip before you tour: Getting pre-approved first turns “I hope this works” into “I know my number,” and it shows sellers you’re ready to act.
You don’t have to memorize this. A good agent walks you through every step, and you can meet our team to see who you’d be working with.
What Mistakes Should First-Time Buyers Avoid?
Many costly first-timer mistakes happen before the offer. Three common ones are skipping pre-approval, draining every dollar of savings into the down payment, and shopping above budget, and all three are avoidable with a clear plan and honest numbers.
Watch for these in particular:
- Touring before pre-approval. You’ll fall for homes you can’t yet act on, and lose to buyers who can.
- Forgetting closing costs. Beyond the down payment, plan for closing costs, which are separate and real.
- Ignoring program deadlines. Assistance funds can run out mid-year, so move on eligibility checks early.
- Big purchases mid-process. A new car loan or large credit charge before closing can sink your approval.
- Going it alone in a high-cost market. In the Tri-Valley, small pricing and negotiation missteps cost real money.
Why stress this? Because each mistake is fixable in advance and costly afterward. A short conversation with a lender and a local agent prevents nearly all of them.
Why Work With a Local, Multilingual Tri-Valley Agent?
A local agent’s value shows up most for first-time buyers, who navigate the process for the very first time. 88% of buyers used an agent or broker in both NAR’s 2024 and 2025 Profiles. For a first-time buyer, that guidance can mean fewer mistakes and a stronger offer.
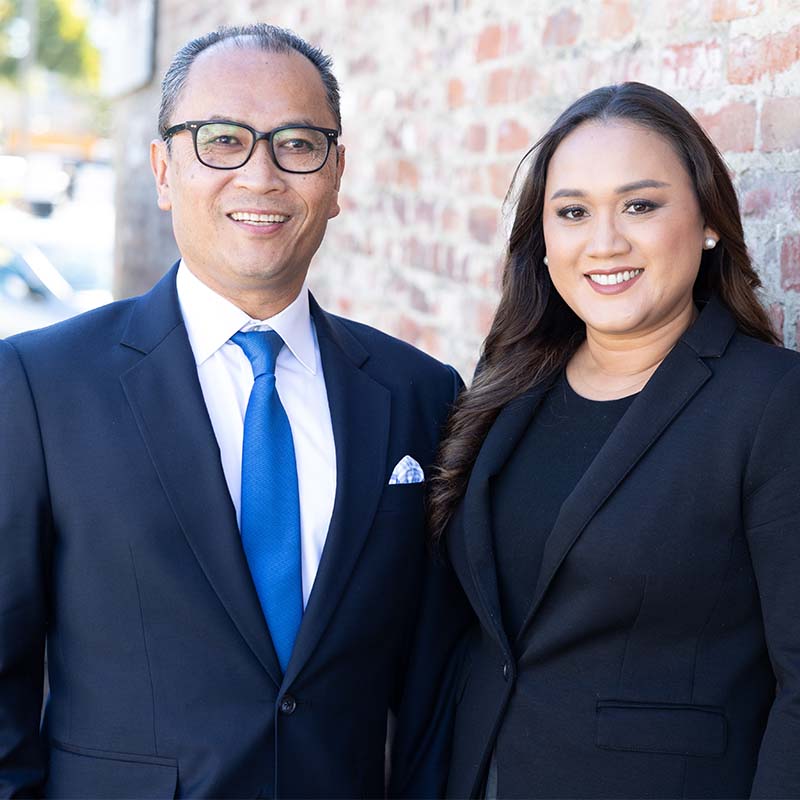
Local matters here specifically. Mony Nop, a REALTOR® (CA DRE# 01813021) with Compass, has been licensed in California real estate since 2007 and is a former Livermore Police officer with 17 years on the force. That’s not a sales pitch; it reflects a career built in this community. Beyond real estate, Mony is a longtime community leader who has twice run for mayor of Livermore.
There’s a second advantage many families value: the team serves clients in English, Khmer, Thai, and Vietnamese. For a multigenerational or multilingual household, being able to ask questions in your own language during the biggest purchase of your life removes a real barrier. Being able to work through the purchase in your own language changes how the whole process feels. In 2017, the National Association of REALTORS® recognized him with a Good Neighbor Awards honorable mention for his work with the Mony Nop Foundation. His ongoing local philanthropy reflects how deeply rooted the team is in this community, not just this market.
If you’re just getting oriented, our guide to living in Livermore, CA is a warm, practical introduction to the area you may soon call home.
Frequently Asked Questions
Who qualifies as a first-time home buyer in California?
CalHFA defines a first-time homebuyer as someone who has not owned and occupied their home in the last three years and has not lived in a home owned by a spouse during that time. That means some prior owners can qualify again. Exceptions may apply, so confirm with a CalHFA-approved lender.
Do I need 20% down to buy in the Tri-Valley?
No. Many first-time buyers use loans that require far less than 20% down, and California assistance programs like MyHome can help with the down payment (CalHFA). Putting less than 20% down usually means paying mortgage insurance, so weigh the trade-off with your lender.
Are California down payment assistance funds guaranteed?
No. Assistance programs depend on state funding, and money can run out during the year, as it has for at least one CalHFA down payment program in the past. Amounts, income limits, and eligibility also change annually. Check current availability with CalHFA and a CalHFA-approved lender early, rather than assuming a program is open.
How much should I budget beyond the down payment?
Plan for closing costs, property taxes, homeowners insurance, any HOA dues, and a maintenance reserve. The 28/36 affordability guideline keeps housing at 28 to 35 percent of gross income (Consumer Financial Protection Bureau). With California’s homeownership rate between 55.3% and 56.8% in 2023 (U.S. Census Bureau), realistic budgeting is the difference-maker for first-time buyers here.
Is it worth using a real estate agent as a first-time buyer?
Yes. 88% of buyers used an agent or broker in both NAR’s 2024 and 2025 Profiles, and first-timers benefit most from that guidance. A local Tri-Valley agent helps you compare neighborhoods, structure a competitive offer, and avoid costly missteps in a high-priced market.
Ready to Buy Your First Tri-Valley Home?
Your first home purchase in Livermore, Pleasanton, Dublin, San Ramon, or Danville doesn’t have to be overwhelming. Start by checking your eligibility for California first-time buyer programs, get pre-approved so you know your real number, and lean on a local team that knows this process well.
When you’re ready to take the next step, explore our buyer resources or meet the Mony Nop Real Estate Team. We’ll help you move from “someday” to “welcome home,” in English, Khmer, Thai or Vietnamese.
This guide is for general information only and is not legal, tax, or financial advice. California assistance programs change frequently; verify all current terms, rates, and eligibility with CalHFA and a licensed lender. Equal Housing Opportunity.
Sources
- National Association of REALTORS®, “First-Time Home Buyer Share Falls to Historic Low of 21%, Median Age Rises to 40” (2025), retrieved 2026-09-21, https://www.nar.realtor/press-releases/first-time-home-buyer-share-falls-to-historic-low-of-21-median-age-rises-to-40
- National Association of REALTORS®, 2024 Profile of Home Buyers and Sellers, Highlights, retrieved 2026-09-21, https://www.nar.realtor/sites/default/files/2024-11/2024-profile-of-home-buyers-and-sellers-highlights-11-04-2024_2.pdf
- California Housing Finance Agency (CalHFA), MyHome Assistance Program, retrieved 2026-09-21, https://www.calhfa.ca.gov/homebuyer/programs/myhome.htm
- U.S. Census Bureau, Housing Vacancies and Homeownership, Table 3 (Homeownership Rates by State) and Table 14 (Homeownership Rates for the US and Regions), retrieved 2026-09-21, https://www.census.gov/housing/hvs/data/rates.html and https://www.census.gov/housing/hvs/data/histtabs.html
- Consumer Financial Protection Bureau, “Your Money, Your Goals” debt-to-income calculator, retrieved 2026-09-21, https://files.consumerfinance.gov/f/documents/cfpb_your-money-your-goals_debt_income_calc_tool_2018-11_ADA.pdf
